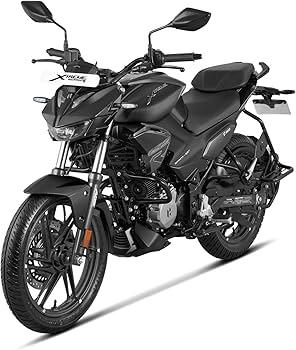
The Hero Xtreme 125R can be attractive to riders wanting an affordable step into sporty 125 cc motorcycles. Financing may spread the initial expense, but the monthly EMI depends on more than the bike’s price. Interest method, deposit, tenure, credit assessment and additional lender charges all affect what ownership actually costs. A clear comparison keeps the motorcycle budget realistic.
Know what motorcycle you are financing
Hero’s Xtreme 125R specification lists a 124.7 cc fuel-injected engine and a five-speed gearbox. The published output is 11.4 bhp and 10.5 Nm, making it a distinctive option within the commuter category. Dealers may offer versions with different braking systems and equipment. Write down the exact trim and production year before comparing loans.
The ex-showroom price is only the starting point for an acquisition budget. Registration, insurance and protective equipment need attention, while optional accessories should be separated. Do not use a loan calculator with an outdated online price when the showroom has quoted a different amount. Accurate principal inputs prevent misleading EMI results.
Interest rates are individual quotations
A lender may consider your credit history, income, repayment obligations, loan size, employment stability and policy when assessing an application. There is no single guaranteed two-wheeler loan interest rate for every buyer. Promotional advertisements often describe conditions that may not apply to a particular applicant. Request written terms rather than relying on an indicative banner.
Check whether the quoted percentage is an annual reducing-balance rate or a flat-rate presentation. Those methods calculate interest differently, so equal numeric percentages need not create equal repayment totals.
How the down payment changes the picture
A higher initial payment normally reduces the financed amount and can lower total interest when other terms remain constant. However, using all available savings as a deposit can create problems if an unexpected household expense follows. Balance a sensible down payment against a cash reserve and predictable monthly instalment.
Illustratively, a motorcycle purchase with Rs. 30,000 available as deposit needs a different loan principal from the same purchase with Rs. 10,000 down. The difference is straightforward, but the available loan-to-value percentage and treatment of other charges depend on the lender. Clarify whether insurance and registration can be financed or must be paid separately.
Compare repayment tenures carefully
Shorter tenures generally produce larger EMIs and less time for interest to accrue. Longer tenures ease monthly payments but can increase total borrowing cost. Build comparisons with identical principal amounts and the same rate, then change only the repayment period. This reveals the trade-off rather than hiding extra cost behind an affordable-looking figure.
A low EMI can also be misleading when an optional product or fee has been bundled into the loan. Choose a term that still fits expected maintenance and insurance renewals during the borrowing period.
Worked EMI example without an assumed offer
Consider a purely illustrative principal of Rs. 1,00,000 at a reducing annual rate of 12% for 36 monthly payments. Standard calculations produce an instalment of approximately Rs. 3,321, with rounding differences possible. The example excludes processing fees and other lender charges, and no applicant is guaranteed these conditions.
The purpose of the illustration is to show how rate, amount and term connect. Enter your own dealer quotation and written lender rate before making a decision. Verify whether the EMI includes all financed expenses. The seller’s preferred payment plan may not be the lowest-cost offer available to you.
Fees and early repayment rules matter
Some loans include processing, documentation and overdue-payment charges. The conditions for prepayment, part payment or foreclosure may also differ. Review these before signing, particularly if you expect to reduce your outstanding balance with future savings. Avoid assuming that every early payment automatically eliminates charges.
Request a copy of the sanction letter and repayment schedule. Read consent forms for optional insurance or other products. If the amount in the documents differs from the discussed quotation, ask for a corrected schedule before agreeing. Retain receipts and payment references throughout the loan.
A motorcycle has costs outside its EMI
The Xtreme 125R needs petrol, scheduled engine maintenance, chain lubrication, tyres and brake attention. Sportier tyre dimensions may change replacement expenses compared with an entry-level commuter. Set aside money for a suitable helmet, gloves and weather protection. Financing affordability is not established by comparing EMI to income alone.
Estimate how much you travel each month and allow fuel costs to vary with congestion and riding habits. A comfortable loan leaves space for those expenses rather than forcing maintenance delays.
Credit conduct during ownership
Make instalment payments by the due date using authorised channels. Missed payments can result in charges and adverse credit reporting depending on the circumstances. Keep emergency funds so routine repairs do not compete with repayment obligations. If income changes unexpectedly, contact the lender through official channels before an instalment falls due.
Avoid applying for several finance offers without understanding how enquiries and eligibility assessments work. Compare written offers by complete cost rather than slogans about instant approval. A legitimate lender should explain its pricing and required documents clearly.
Ask the lender how a missed payment is identified and communicated. Keep a separate emergency amount instead of exhausting your savings. Confirm repayment dates before authorising an automatic debit instruction.
Finance the 125R only within a complete budget
The Xtreme 125R may make sense when you enjoy its riding style and can comfortably meet both repayment and maintenance costs. Confirm the exact model variant, obtain competing lender quotations and compare the full repayment totals. The right interest rate is the one supported by transparent terms and a manageable obligation, not merely the smallest advertised EMI.